
// TINY HOUSES & ALTERNATIVE REAL ESTATE
Mobile Dwelling Insurance Options for Life Off-Grid
Comparing mobile dwelling insurance options starts with a deceptively simple question: what, exactly, are you insuring? A registered travel trailer, a permanently parked tiny house and a rooftop sleeping shelter can require entirely different policies. The right coverage follows the structure’s classification, how often it moves and whether it is your primary residence—not the lifestyle label attached to it.
For ultramobile living, the expensive mistake is assuming the vehicle policy covers the whole setup. Your shelter, installed equipment, belongings and liability may sit in separate coverage categories. Before comparing premiums, establish who will insure the complete arrangement and which losses would fall between policies.
Mobile Dwelling Insurance Options by Structure
A towable tiny home may qualify for RV insurance if its construction, documentation and use meet the insurer’s requirements. Full-time residents generally need coverage designed for residential occupancy, rather than a recreational policy intended for occasional trips. Owner-built structures and undocumented electrical work can narrow the available market considerably.
A tiny house fixed to land may instead need homeowners, manufactured-home or specialty dwelling coverage, depending on its construction and local classification. A rooftop shelter is a different proposition: ask about an endorsement for permanently installed vehicle accessories or a specialty equipment policy. Calling something a dwelling does not make it eligible for residential insurance.
The Coverage That Matters Beyond the Shell
Separate physical damage from liability. Collision and comprehensive coverage may protect the host vehicle without fully covering an expensive shelter installation. Personal property coverage addresses belongings, while liability concerns injuries or damage you cause. Once parked and occupied, a setup can create exposures that ordinary auto liability does not address.
Ask how solar panels, batteries, inverters and mounting hardware are treated: installed equipment, separate property or excluded modifications. Then check theft limits and replacement-cost versus depreciated-value settlement. Flood, earthquake, water intrusion, wear and mechanical failure often receive different treatment; weather-resistant construction does not establish insurance coverage. Off-grid work also raises questions about business equipment and use.
Premiums: Compare the Contract, Not Just the Number
As a broad U.S. industry budgeting range, recreational trailer policies can run from a few hundred dollars to roughly annually; full-time occupancy, higher replacement values and specialty tiny-home risks can cost substantially more. These are planning ranges, not WOWLS quotes. Rooftop equipment may be priced as an accessory endorsement rather than a standalone dwelling policy.
Request quotes using identical declared values, deductibles and occupancy details. A cheap premium can conceal low accessory limits or an actual-cash-value settlement that deducts depreciation. Ask whether emergency accommodation, towing and recovery are covered—and whether recovering the vehicle also includes handling the shelter. Remote locations can make an otherwise modest claim logistically expensive.
Movement, Land and the Address Problem
Tell the insurer where the structure normally stays, how frequently it moves and whether anyone lives in it year-round. Transit, storage and occupied use are distinct risks. A policy suitable for a stationary tiny house may not cover highway transport, while recreational coverage may restrict permanent residency. Rental to guests introduces another underwriting category.
Insurance also does not establish permission to occupy land. Zoning, parking rules, sanitation requirements and campsite agreements remain separate considerations. If you lease a pitch or use someone else’s property, clarify responsibility for visitor injuries and utility connections. Give the broker an accurate description rather than trying to fit an unconventional home into a cheaper category.
Where the AutoYurt Concept Fits
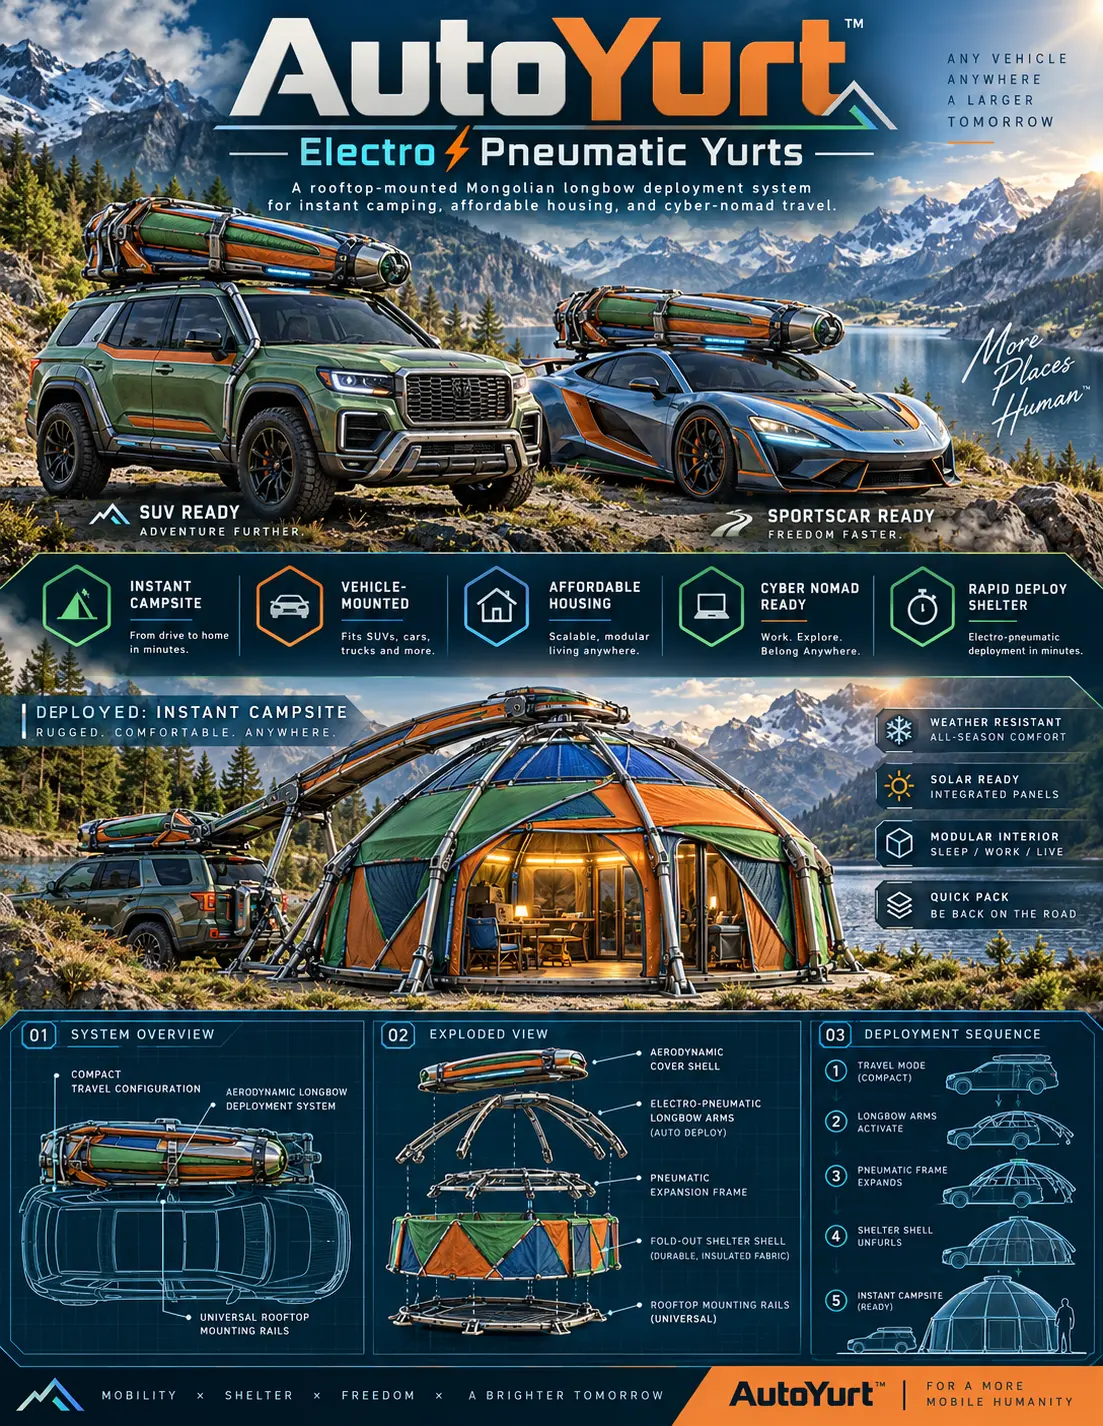
The WOWLS AutoYurt concept explores a rooftop shelter with low-profile longbow housing, electro-pneumatic deployment, an insulated fabric shell and integrated exterior solar panels. Its proposed sleeping and working layout makes the insurance question especially relevant: a carrier would need to understand the host vehicle, attachment method, equipment value and intended occupancy before deciding eligibility.
AutoYurt is a concept, not an available or certified dwelling product, and no insurance eligibility is established. Explore /yurt, then register interest through /contact. As specifications develop, mounting documentation, electrical details, replacement values and repair procedures would help insurers assess a proposed installation. The strongest ultramobile setup is one whose physical design and insurance description match.
Can my car insurance cover a rooftop dwelling or AutoYurt?
Possibly, but do not assume standard car insurance covers the shelter, its contents or liability while you occupy it. Ask the insurer whether attached equipment needs an accessory endorsement, what value limits apply and whether overnight or full-time residential use changes eligibility. Request written confirmation for the specific installation and use. The WOWLS AutoYurt remains a concept, so coverage cannot be presumed; underwriting would depend on eventual specifications, the host vehicle and the carrier’s acceptance.