
// ULTRAMOBILE LIVING & AUTO-YURTS (VEHICLE-MOUNTED SHELTERS)
Land Tax Free Living Spaces via Ultramobile Vehicle Architecture
Real estate property tax assessments perpetually tie homeowners to static coordinates, but switching to nomadic vehicular architecture unlocks legitimate land tax free living spaces. When your shelter mounts directly to universal vehicle rails or a modular chassis rather than sitting on a poured concrete foundation, municipal codes classify it as personal cargo or automotive equipment rather than real property improvements. This crucial distinction completely sidesteps recurring local parcel taxes while preserving uncompromised mobility across public dispersed camping and private leases.
Transitioning away from conventional deeds does not require sacrificing thermal efficiency or modern comfort. Traditional recreational vehicles and tow-behinds often drag thousands of pounds of dead weight, ruin vehicle handling, and decay under harsh weather. The modern off-grid frontier reimagines ancestral nomadic shelters through aerodynamic, electro-pneumatic engineering tailored for agile, everyday adventure rigs.
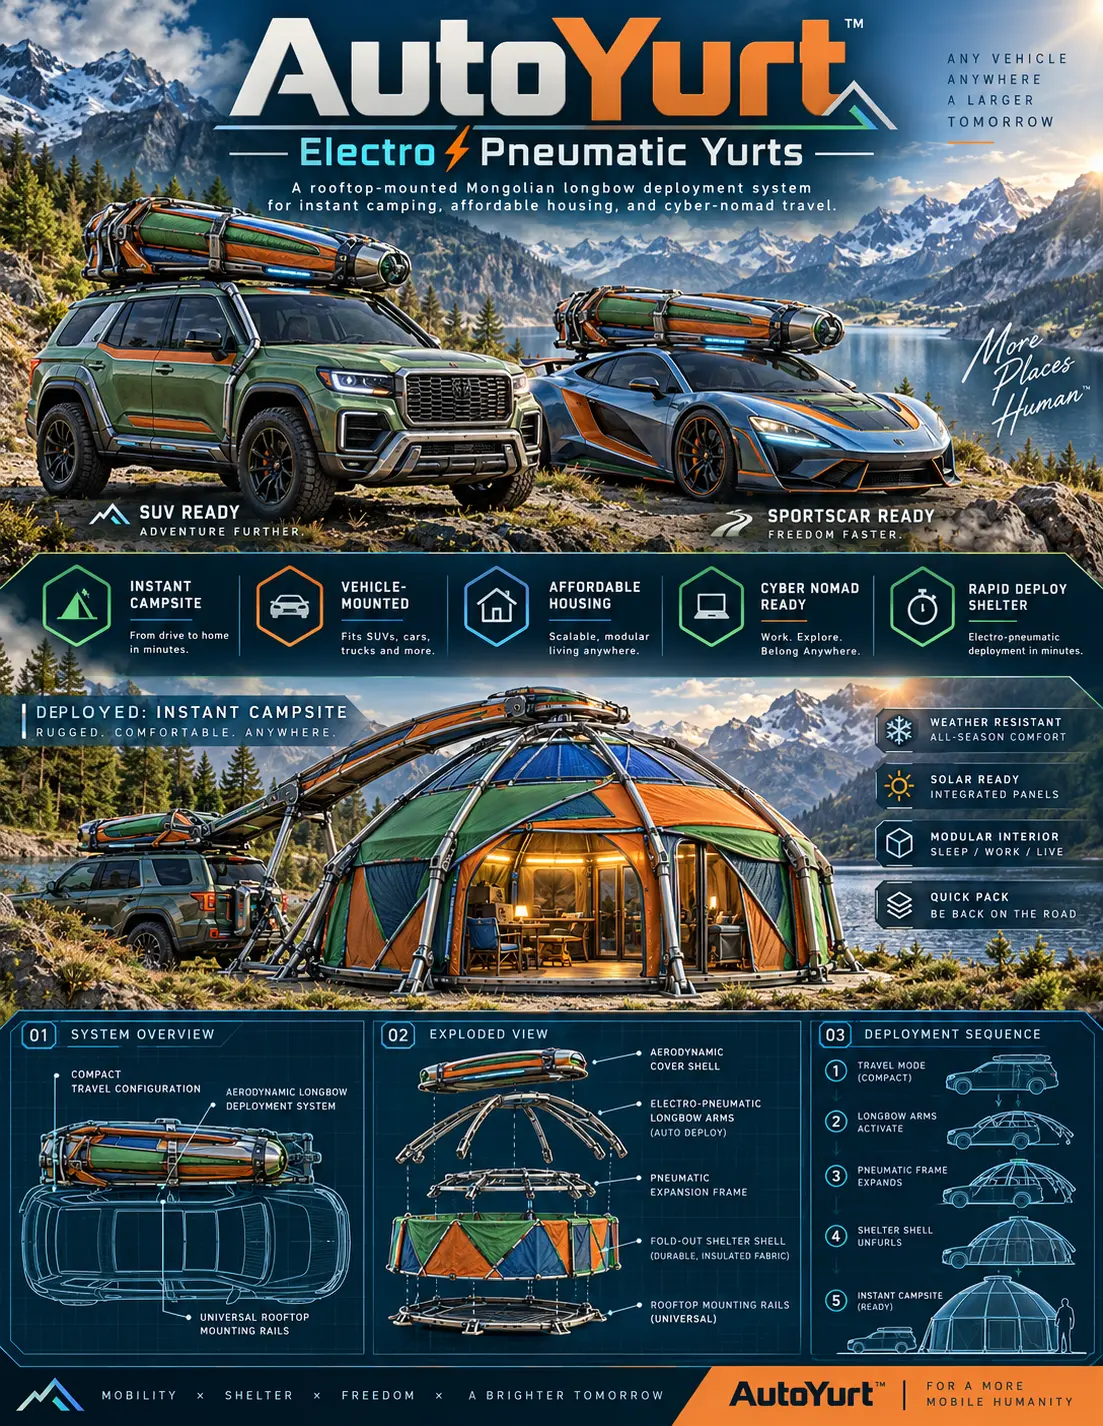
The Mechanics of Land Tax Free Living Spaces
Tax assessors calculate real property levies based on static improvements anchored to the dirt. Industry overland platforms—ranging anywhere from basic entry-level pop-ups around to fully bespoke expedition composite builds exceeding —sidestep permanent land taxation precisely because they remain decoupled from the ground. By staying mobile, occupants navigate regional zoning laws cleanly while sidestepping building permits and escalating assessment rates.
Aerodynamic Engineering in the AutoYurt Ecosystem
The historic dilemma with deployable shelters has been punishing wind resistance and laborious manual setup. WOWLS challenges legacy overlanding with the AutoYurt concept, an electro-pneumatic shelter engineered to secure onto universal vehicle rooftop rails. Housed within a sleek, low-profile longbow aerodynamic shell that limits highway drag, the AutoYurt expands rapidly into an insulated, all-weather dome. Engineered with modular thermal barriers for radical temperature swings and integrated exterior solar arrays, it serves as a high-altitude workstation and sleeping pod without compromising highway handling.
Self-Driving Expedition Rigs for Nomads
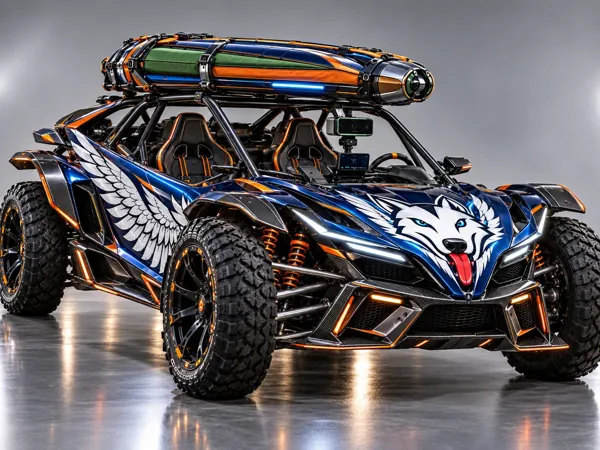
Radical off-grid sovereignty converges with autonomous ground mobility. WOWLS explores this frontier with the Minghan-Class All Electric Tactical Buggy concept, pairing an expedition exoskeleton with instant electric torque and an optional roof-integrated electro-pneumatic yurt sheath. Exploring comma.ai open-source self driving hardware mounts as a conceptual integration—distinguished strictly from certified or factory-tested autonomy—the platform is envisioned to handle highway transit safely before pitching camp off-grid. Interested pioneers can register interest via the official contact portal.
Equipping the Modern Frontier Lifestyle
Sovereignty extends beyond mobile shelters to the physical gear supporting daily life. While advanced mobility platforms and deployable yurt units remain in prototype and waitlist stages, explorers can outfit their everyday kit right now through the WOWLS online storefront. From weather-ready ripstop Performance Jackets and gi-inspired Hero Cargo-Track Pants in the fit collection to insulated hydration gear and cosmic artwork, outfitting for a life beyond fixed property lines begins with purpose-built utility.
How do mobile vehicle shelters legally avoid real estate land taxes?
Tax assessors apply real property taxes exclusively to land and permanent structures attached to the ground via foundations, footings, or permanent utility tie-ins. Vehicle-mounted electro-pneumatic yurts and modular rooftop shelters sit on universal vehicle racks and are classified under law as personal property, cargo, or vehicular accessories. Because they remain mobile, temporary, and unattached to the parcel, they generate zero real estate tax assessments, allowing nomads to maintain flexible living quarters without incurring recurrent property tax obligations.