
// TINY HOUSES & ALTERNATIVE REAL ESTATE
Alternative Mortgage for Tiny House: Finance Your Next Move
Finding an alternative mortgage for tiny house ownership starts with a question most listings skip: are you financing real estate, a movable dwelling, or recreational equipment? The answer determines which lenders will consider your application, what secures the debt, and whether your intended location is legal. A beautiful floor plan cannot fix the wrong loan category.
For buyers exploring ultramobile living, the choice is broader than a tiny house on a trailer. You might want a permanent compact home, a towable cabin, or a vehicle-based shelter for shorter stays. Each serves a different purpose—and buying the least expensive structure does not necessarily produce the lowest monthly housing.
Choosing an Alternative Mortgage for Tiny House Ownership
A tiny house on a permanent foundation may qualify for a conventional mortgage when the property, land, appraisal and construction meet the lender’s requirements. Small size alone is not always disqualifying. More common obstacles include missing permits, limited comparable sales, unconventional construction and loan amounts below a lender’s minimum.
A house on wheels generally falls outside ordinary real-estate mortgage lending. Depending on its documentation and use, financing may instead resemble an RV loan, a personal-property loan or unsecured credit. Before paying a builder’s deposit, ask prospective lenders whether they finance that exact structure and whether full-time occupancy is permitted under their loan terms.
Four Financing Routes Beyond a Standard Mortgage
An unsecured personal loan avoids putting the dwelling up as collateral, but typically means a shorter repayment window and a higher monthly payment than a long mortgage. Typical industry repayment terms often run roughly two to seven years, with pricing dependent on credit, income and lender criteria. Compare APR rather than the advertised interest rate alone.
RV financing can offer longer repayment periods for qualifying recreational units, but a handmade trailer home may not satisfy certification or underwriting requirements. A chattel loan finances personal property rather than the underlying land, where an eligible lender and housing category exist. Home-equity borrowing is another route for existing homeowners, but it puts the property securing that borrowing at risk—not just the new tiny house.
The Site Can Cost More Than You Expect
Separate the dwelling budget from the location budget. Land purchase or pad rent, delivery, grading, utility connections, wastewater arrangements, insurance and permits can change the economics substantially. Off-grid equipment replaces some utility dependence with upfront hardware, maintenance and eventual battery replacement; it does not eliminate infrastructure expenses.
Confirm local rules before committing funds. Ask the planning authority about minimum dwelling standards, permitted residential use, parking duration and whether a wheeled structure can serve as a primary residence. Obtain site-specific quotes rather than relying on a national average. A cheap parcel without legal access or an acceptable wastewater solution can become the most expensive part of the project.
When a Mobile Shelter Fits Better Than a Tiny House
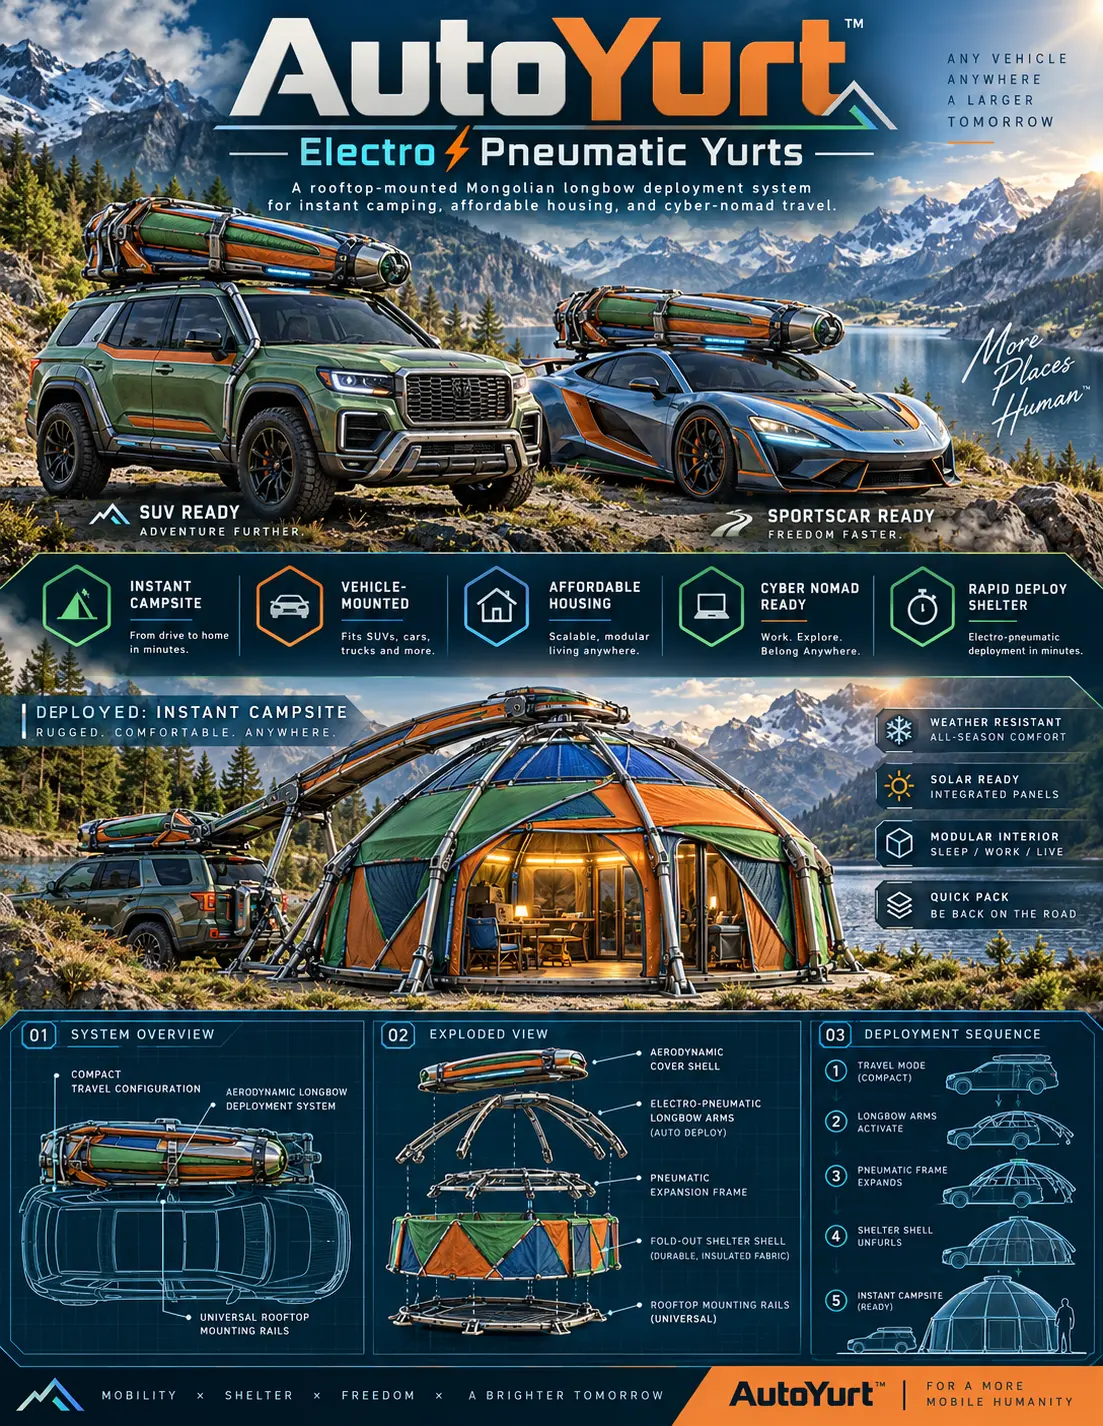
If your actual goal is weekend exploration or a workspace at changing destinations, financing a residential structure may solve the wrong problem. WOWLS! AutoYurt is a concept for an electro-pneumatic rooftop shelter, combining a low-profile longbow housing, powered deployment, an insulated fabric shell and integrated exterior solar panels intended for off-grid device power.
The proposed system targets cars, SUVs, trucks and performance platforms through a universal rooftop-rail approach. Vehicle-specific fit, roof loading and final specifications would still need confirmation. It is not an available, certified dwelling or a substitute for lawful residential occupancy. Register interest through /contact and join the AutoYurt waitlist; no retail price or financing offer is established here.
Compare the Whole Commitment, Not the Deposit
Request quotes using the same purchase amount, down payment and repayment period. Compare APR, origination fees, total repayment, early-payment provisions and any balloon balance. With builder-arranged financing, establish who actually lends the money and how payments connect to construction milestones. Avoid funding an entire build before contractual delivery protections are clear.
Match the commitment to your time horizon. A permitted foundation home suits long-term occupancy; a qualifying towable unit prioritizes relocation; a rooftop shelter concept addresses a lighter travel use case. Explore /yurt for the WOWLS! ultramobile direction and /about for its exploration-led thesis, while treating mortgage eligibility and legal housing status as separate decisions.
Can I finance a tiny house without a traditional mortgage?
Yes. Depending on the structure, documentation and intended use, options may include a personal loan, qualifying RV financing, a chattel loan or borrowing against an existing home’s equity. A permitted tiny house permanently attached to owned land may also qualify for mortgage financing. Compare total repayment and site expenses, not just the monthly loan payment. Confirm that both the lender and local authority accept your intended occupancy before placing a deposit; financing approval does not establish permission to live there.